By Sola Alabadan
It was with good intent that the National Assembly included a prescribed Minimum Capital Requirements in Section 15 of the Nigerian Insurance Industry Reform Act (NIIRA) 2025, which became effective on July 31 of the same year.
For record purposes, non life insurance companies were required to maintain a minimum capital of ₦15 billion, while life assurance companies were mandated to increase their capital to a minimum of ₦10 billion and reinsurance firms were asked to raise their capital base to a minimum of ₦35 billion.
The insurance operators were given a period of 12 months, which expired on July 31, 2026, to meet up with the new minimum capital requirements.
The truth is that the Nigeria’s insurance industry has emerged from its latest recapitalisation exercise with a significantly stronger capital base, but the more important test is now whether the additional capital can translate into better services for policyholders, stronger underwriting capacity and a greater contribution to the Nigerian economy.
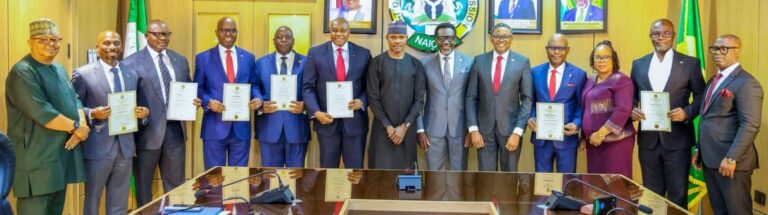
The National Insurance Commission (NAICOM) has confirmed that 48 insurance companies and two reinsurers met the new minimum capital requirements, while six insurance licences were cancelled after the affected operators failed to meet the regulatory threshold.
NAICOM subsequently commenced the issuance of new operating licences to companies that successfully met the requirements.
The recapitalisation exercise, no doubt, has significantly altered the structure of the insurance market. According to NAICOM, about N1.079 trillion was mobilised through the recapitalisation exercise, comprising fresh capital and existing funds that strengthened the financial position of operators.
But with the recapitalisation hurdle now behind the industry, attention is shifting to what the stronger capital base will achieve.
Stakeholders are now asking whether the additional funds will enable insurers to underwrite larger and more complex risks, settle claims faster, retain more risks within Nigeria and expand insurance coverage to millions of Nigerians who remain outside the formal insurance market.
For an industry whose penetration remains below one per cent, the significance of the reform therefore extends far beyond the balance sheets of insurance companies.
Beyond raising capital
The Commissioner for Insurance and Chief Executive Officer of NAICOM, Olusegun Omosehin, has repeatedly stressed that recapitalisation was never intended to be an end in itself.
According to Omosehin, the additional capital should create capacity for insurers to underwrite larger and more complex risks, strengthen claims-paying ability, innovate, improve customer experience and retain more risks within Nigeria.
He has also identified claims payment as one of the most visible measures of the value of insurance to policyholders.
For years, inadequate capital and weak balance sheets have been cited among the factors limiting the ability of local insurers to retain substantial portions of major risks in sectors such as oil and gas, aviation, marine, infrastructure and other specialised businesses.
The stronger capital base is expected to give Nigerian insurers greater financial capacity to compete for such risks.
It could also reduce excessive dependence on foreign insurance markets and allow more premiums, expertise and risk-management opportunities to remain within the domestic economy.
Trust remains a major challenge
Despite the stronger financial position of operators, the industry continues to face a number of structural challenges, including a trust deficit, limited consumer awareness, affordability constraints, weak distribution networks and concerns about the speed and experience of claims settlement.
These challenges are particularly significant because the ultimate test of an insurance policy for most customers is what happens when a loss occurs.
The Chairman of the Nigerian Insurers Association (NIA), Ebelechukwu Nwachukwu, has acknowledged the broader challenge, saying the reform should be used to strengthen market conduct, consumer confidence, innovation and the industry’s contribution to the economy.
Nwachukwu described the recapitalisation as a foundation for stronger players with the capacity to underwrite large and complex risks, mobilise long-term capital and invest in digital transformation.
She also stressed that the real test would be converting stronger balance sheets into underwriting capacity, innovation, improved claims service and wider insurance penetration.
New regulatory era
The focus on capital is also coming at a time when NAICOM is preparing to introduce another major regulatory reform.
The commission has appointed Ernst & Young as consulting actuary for the implementation of a Risk-Based Capital (RBC) framework, which will align insurers’ capital requirements more closely with the risks inherent in their businesses.
NAICOM said the framework is intended to strengthen financial stability and policyholder protection.
The move suggests that the new minimum capital thresholds may not represent a permanent finish line for insurance companies.
Instead, insurers are likely to face greater scrutiny over the quality and risk profile of their businesses, governance structures, capital adequacy, underwriting practices and ability to withstand financial and operational shocks.
The implication is that financial strength will increasingly have to be supported by prudent risk management, effective governance and sound underwriting practices.
Technology, innovation take centre stage
Industry observers also see the recapitalisation as an opportunity for insurers to invest more aggressively in technology, data, product development and alternative distribution channels.
The Chief Executive Officer of Consolidated Hallmark Insurance, Mary Adeyanju, said stronger capital should create opportunities for greater collaboration between insurers and brokers, investment in technology and the development of products that respond more closely to consumers’ needs.
For brokers, whose relationships with policyholders give them a direct understanding of consumer concerns, the post-recapitalisation challenge will be to ensure that the stronger financial position of insurers translates into products that customers understand, can afford and consider valuable.
The increased capital base could also enable operators to develop innovative products targeted at underserved markets and expand access through digital platforms and other alternative distribution channels.
Pressure to deliver returns
A larger capital base provides insurers with greater capacity to take on bigger risks, but it also creates pressure to generate adequate returns for shareholders who provided the funds.
This could force operators to become more disciplined in underwriting, pricing, risk selection, operating costs and technology investments.
The recapitalisation has reduced the number of licensed operators and is likely to result in a more concentrated market, with stronger institutions competing for business across major corporate and retail segments.
While this could create economies of scale and improve financial resilience, stakeholders will also need to ensure that consolidation does not weaken competition or reduce the range of products available to consumers.
NAICOM has already warned newly licensed operators that the next phase requires prudent utilisation of capital, stronger corporate governance, transparency and accountability.
The regulator has equally made it clear that its expectations extend beyond compliance with minimum capital requirements.
What does recapitalisation mean for policyholders?
NAICOM wants insurers to deploy the new capital towards larger risks, stronger claims-paying capacity, innovation and improved customer service, while increasing the industry’s contribution to infrastructure financing and economic development.
For policyholders, however, the most important question after recapitalisation may be relatively simple: what changes when a claim is made?
If the answer is faster claims settlement, fewer disputes, better service and stronger financial protection, the reform would begin to demonstrate its value beyond the financial statements of insurance companies.
But if the additional capital merely produces larger balance sheets without materially expanding coverage, improving claims experience or bringing millions of uninsured Nigerians into the formal insurance market, the broader objective of the reform would remain unfinished.
The harder assignment begins
The post-recapitalisation era is consequently less about celebrating the amount of capital raised and more about converting that capital into capacity.
For NAICOM, the next stage is expected to focus on stronger underwriting, claims payment, innovation, governance and consumer protection.
For the NIA and operators, the challenge is to use the stronger financial foundation to deepen public confidence, develop products that meet changing consumer needs and expand the reach of insurance across the economy.
The recapitalisation has provided the industry with a stronger financial platform. The next measure of success will be whether that platform produces stronger insurers, better protection for policyholders and deeper insurance penetration.
With the recapitalisation hurdle now behind the industry, the harder assignment begins: turning stronger insurers into a stronger insurance market.
Bigger expectations
According to NAICOM boss, the stronger capital base would enable insurance companies to underwrite larger and more complex risks, improve their capacity to meet policyholder obligations and retain more risks within Nigeria.
He added that the recapitalisation was also expected to enhance the industry’s ability to support major investments and economic activities while improving confidence in insurance as a critical component of the financial system.
More Stories
PenCom To Start Implementing Minimum Pension Guarantee From October 29
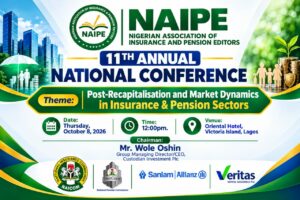
Insurance, Pension Stakeholders Back NAIPE Conference On Post-Recapitalisation Market Dynamics
NANS Condemns Attempts To Derail Insurance Recapitalisation Exercise